Adjusted Gross Income
Adjusted gross income, or AGI, is your total taxable income for the year minus certain items the IRS calls adjustments to income. It is one of the most important numbers on a U.S. federal tax return.
On Form 1040, AGI is near the bottom of the first page, on the line labeled "adjusted gross income" (line 11a on the 2025 form, line 11 on earlier ones).
AGI is not the amount you pay tax on. That number is your taxable income, which you get by subtracting your standard or itemized deduction (and a few other deductions) from AGI. AGI comes first, and many other parts of your return depend on it.
In this lesson, you will learn
- what adjusted gross income is and why it matters
- what counts as total income and which adjustments you can subtract
- how to calculate AGI, and then taxable income, step by step
- how AGI differs from taxable income and from modified AGI
Why AGI Matters
- Eligibility for tax breaksMany credits and deductions shrink or disappear once your AGI (or a version of it called modified AGI) passes a limit.
- Medical expense deductionIf you itemize, you can only deduct medical costs above 7.5% of your AGI.
- Filing electronicallyWhen you e-file, you may be asked for last year's AGI to confirm your identity.
- Outside the IRSStudent aid forms, some loan applications and many state tax returns start from your federal AGI.
Your AGI is $40,000 and you itemize. You had $5,000 of medical costs. How much of it can you deduct?
Show answer
$2,000. 7.5% of $40,000 is $3,000. Only the part above that counts: $5,000 − $3,000 = $2,000.
Step 1: Add Up Your Total Income
Total income includes taxable income from all sources, such as:
- Wages, salaries and tips
- Taxable interest and ordinary dividends
- Taxable IRA distributions, pensions and annuities
- The taxable part of Social Security benefits
- Capital gains (or losses)
- Business income from self-employment
- Rental income, unemployment compensation, gambling winnings and other income
- Alimony received, but only under a divorce or separation agreement signed before 2019
The diagram below shows how everything fits together, from total income down to taxable income:
Ana earned $41,000 in wages, $6,000 in tips and $120 of interest. What is her total income?
Show answer
$47,120. Tips and interest are income too: $41,000 + $6,000 + $120 = $47,120.
Step 2: Subtract Your Adjustments to Income
Adjustments are listed on Schedule 1 (Part II) of Form 1040. You can claim them whether you take the standard deduction or itemize. Common ones:
| Adjustment | Key rule or limit |
|---|---|
| Educator expenses | For K–12 teachers, counselors, principals and aides who work at least 900 hours a school year; capped each year ($300 per educator for 2025) |
| Student loan interest | Up to $2,500 of interest paid a year; phases out at higher incomes |
| Deductible IRA contributions | Traditional IRA only; the deductible amount depends on income and workplace retirement plans |
| Health savings account (HSA) | Contributions you made yourself, not through payroll |
| Half of self-employment tax | For people who work for themselves |
| Self-employed health insurance | Premiums for yourself and your family, up to your business profit |
| Self-employed retirement plans | SEP, SIMPLE and solo 401(k) contributions |
| Alimony paid | Only under a divorce or separation agreement signed before 2019 |
Not adjustments: the standard deduction and itemized deductions. They are subtracted after AGI, so they lower your taxable income but not your AGI. The deductions for tips, overtime, car loan interest and seniors that began in 2025 work the same way.
- Total income: $45,000 + $200 = $45,200.
- Student loan interest counts only up to $2,500 a year, so her adjustment is $2,500, not $3,100.
- AGI = $45,200 − $2,500 = $42,700.
Lena's AGI is $42,700.
Does taking the standard deduction lower your AGI?
Show answer
No. The standard deduction is subtracted after AGI. It lowers your taxable income, not your AGI.
Adjusted Gross Income at a Glance
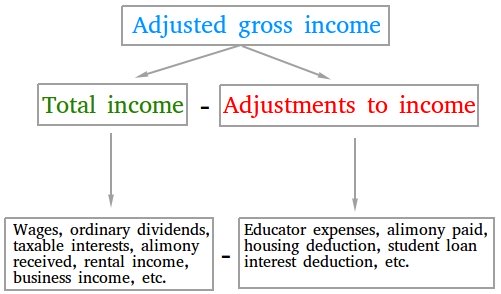
This summary chart puts the two steps side by side: total income on the left, adjustments to income on the right, and adjusted gross income as the difference.
Example 1: A Teacher With a Second Job
Problem
In 2025, Peter is a high school math teacher. He earned a salary of $52,000. He also tutored at a learning center for 20 weeks at $200 a week, and earned $50 of interest on a savings account. He spent $500 of his own money on classroom supplies and paid $1,200 in student loan interest. What is Peter's AGI?
Tutoring wages: $200 × 20 weeks = $4,000
| Item | Amount |
|---|---|
| Teaching salary | $52,000 |
| Tutoring wages | $4,000 |
| Interest | $50 |
| Total income | $56,050 |
| Educator expenses (2025 cap: $300) | − $300 |
| Student loan interest | − $1,200 |
| Adjustments to income | $1,500 |
| Adjusted gross income | $54,550 |
Peter spent $500 on supplies, but the educator expense deduction was capped at $300 for 2025, so only $300 counts.
From AGI to taxable income: Peter is single and takes the standard deduction, which was $15,750 for a single filer in 2025.
Taxable income = $54,550 − $15,750 = $38,800
Example 2: A Self-Employed Investor
Problem
In 2025, William earned $80,000 of net rental income from real estate, $50,000 from the taxable part of an annuity, and $20,000 of interest. He also made a $100,000 profit selling educational software as a self-employed business owner. He paid $100,000 in alimony under a divorce finalized in 2016, and $12,000 for his own health insurance. What is William's AGI?
| Item | Amount |
|---|---|
| Rental income | $80,000 |
| Annuity (taxable part) | $50,000 |
| Interest | $20,000 |
| Business profit | $100,000 |
| Total income | $250,000 |
| Alimony paid (pre-2019 divorce) | − $100,000 |
| Self-employed health insurance | − $12,000 |
| Half of self-employment tax | − $7,065 |
| Adjustments to income | $119,065 |
| Adjusted gross income | $130,935 |
Where does $7,065 come from? For profits below the yearly Social Security wage limit, self-employment tax is 15.3% of 92.35% of business profit:
$100,000 × 0.9235 = $92,350
$92,350 × 0.153 = $14,129.55
Half of that is $7,064.78, which rounds to $7,065.
If William's divorce had been finalized in 2019 or later, he could not deduct the alimony, and his AGI would be $100,000 higher: $230,935.
AGI and Modified AGI (MAGI)
Some tax rules use modified adjusted gross income instead. MAGI starts with AGI and adds back certain items, such as tax-exempt interest or the student loan interest deduction. Which items get added back depends on the rule, so there isn't one single MAGI. For most people, MAGI is the same as AGI or very close to it.
Can MAGI be lower than AGI?
Show answer
No, not with add-backs like these. MAGI starts with AGI and adds items back, so it is the same as AGI or higher.
Practice Problems
1. Maria earned $68,000 in wages, $300 in interest and $700 in dividends. She put $5,000 into a fully deductible traditional IRA and $2,000 into an HSA on her own. What is her AGI?
Show answer
Total income = $68,000 + $300 + $700 = $69,000
Adjustments = $5,000 + $2,000 = $7,000
AGI = $69,000 − $7,000 = $62,000
2. In 2025, a married couple were both K–12 teachers. Together they earned $120,000. Each spent $450 on classroom supplies. What is their AGI on a joint return?
Show answer
The 2025 cap was $300 per educator, so each spouse can deduct only $300 of the $450. The adjustment is $300 + $300 = $600.
AGI = $120,000 − $600 = $119,400
3. A restaurant server earned $22,000 in wages and $18,000 in qualified tips in 2025. She is single and has no adjustments. What are her AGI and taxable income?
Show answer
Tips are income, so total income = $22,000 + $18,000 = $40,000. With no adjustments, AGI = $40,000.
The tips deduction is subtracted after AGI, along with the 2025 standard deduction of $15,750:
Taxable income = $40,000 − $15,750 − $18,000 = $6,250
The way AGI is calculated stays the same from year to year, but dollar limits, line numbers and some deductions change. The examples use 2025 figures. Before filing, check the current Form 1040 instructions at irs.gov or ask a tax professional.
Summary
- AGI = total income − adjustments to income. It is on line 11a of the 2025 Form 1040.
- Total income includes wages, tips, interest, dividends, business, rental and retirement income, and other taxable income.
- Adjustments include educator expenses ($300 cap for 2025), student loan interest (up to $2,500), deductible IRA and HSA contributions, and half of self-employment tax.
- The standard or itemized deduction, and the 2025 deductions for tips, overtime, car loan interest and seniors, come after AGI: they lower taxable income, not AGI.
- Taxable income = AGI − deductions. For a single filer taking the standard deduction in 2025, that means AGI − $15,750.
Test Yourself: 10-Question Quiz
Now check what you learned. Every answer is explained, and each time you play you get new questions. All questions use 2025 figures.
Quiz complete!
Have A Great Basic Math Word Problem?
Share it here with a very detailed solution!
This form is being moved to the new site. It will be connected before launch.
What Other Visitors Have Said
Click below to see contributions from other visitors to this page...
Calculating Gross Earnings Not rated yet
Bryan works in a men's clothing store. He earns a base salary of $350 per week plus his commission is 5% on all sales. If Bryan's sales in one week total …